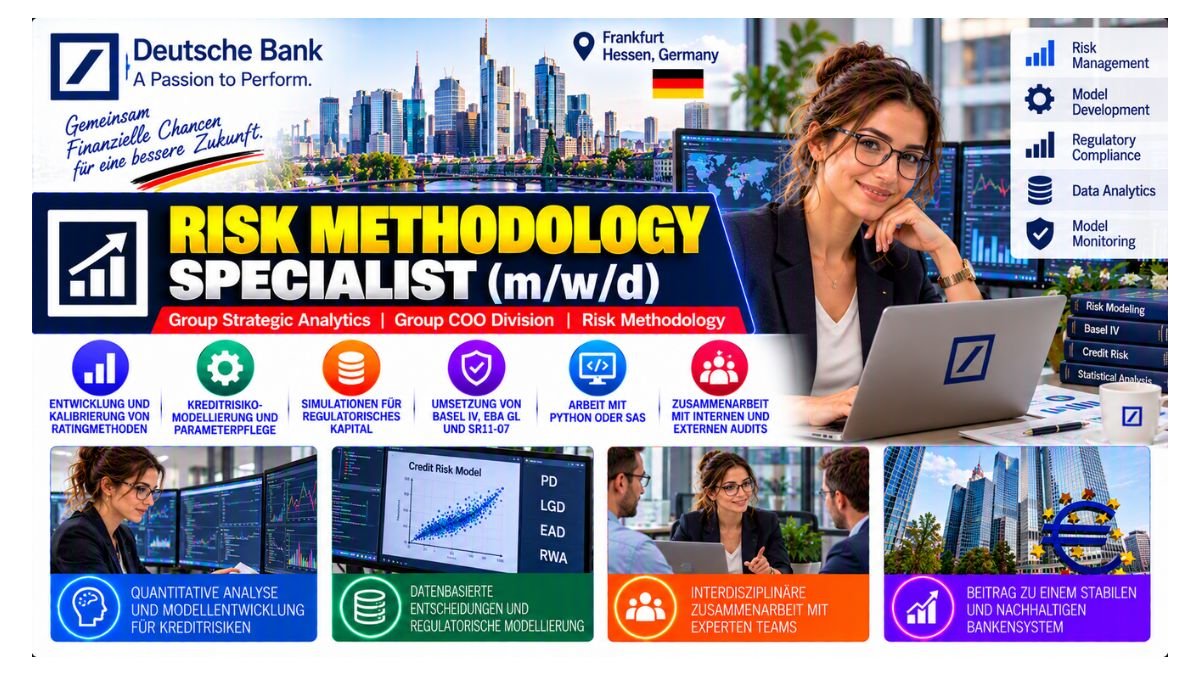
Deutsche Bank — eine der weltweit führenden Banken — sucht für die Risk Methodology-Abteilung als Teil der Group Strategic Analytics / Group COO Division in Frankfurt, Hessen einen Risk Methodology Specialist (m/w/d). Diese zentrale Rolle entwickelt, kalibriert und pflegt Ratingmethoden und Kreditrisikoparameter für Deutsche Bank Portfolien (Fokus: DE Retail Germany Portfolio), führt Simulationen zur Auswirkung auf das regulatorische Kapital durch, verbessert interne Modelle unter Berücksichtigung von Basel IV, EBA GL, und SR11-07 Standards, und unterstützt regulatorisches Model Monitoring sowie interne und externe Audits. Voraussetzungen: Master oder PhD in Mathematik, Statistik oder vergleichbarer quantitativer Disziplin, Kenntnisse im Kreditrisikomodellierung, sicherer Umgang mit Python oder SAS, verhandlungssicheres Deutsch und Englisch. Kontakt: nana.darko@db.com.
About Deutsche Bank — Group Strategic Analytics / Risk Methodology Frankfurt
Organisation: Deutsche Bank — one of the world’s leading financial institutions — Risk Methodology Department within Group Strategic Analytics / Group COO Division, playing a central role in developing bank-wide risk assessment methods supporting resource allocation, risk appetite management, credit decisions, and adequate capital allocation
Culture: “Eine Kultur des offenen Feedbacks und des Dialogs mit den Mitarbeitenden” — open feedback and constructive dialogue as the foundation of a working environment that enables the simultaneous mastering of professional and personal challenges — with flexible working models, Teilzeit options, and hybrid working
Role: Risk Methodology Specialist — development/calibration and maintenance/recalibration of rating methods and credit risk parameters for Deutsche Bank portfolios (focus: DE Retail Germany Portfolio), regulatory capital impact simulations, Basel IV/EBA GL/SR11-07 compliance, model monitoring, and audit participation
Contact: Nana Darko — nana.darko@db.com — for Rekrutierungsprozess questions
Why This Risk Methodology Specialist Role at Deutsche Bank Stands Out
Bankweite Methodologische Wirkung — Group COO Division: Work at the methodological core of one of the world’s largest banks — in a department whose rating methods and credit risk parameters directly influence capital allocation, risk appetite management, and credit decisions across the Deutsche Bank Group, with a level of analytical influence and professional visibility that few risk roles in the German banking sector can match
Basel IV & EBA GL — Regulatorisch Relevantes Modellierungsumfeld: Apply and develop expertise at the frontier of banking regulation — Basel IV, EBA GL, and SR11-07 are among the most consequential regulatory frameworks in European financial risk management, and experience developing internal models to these standards at Deutsche Bank is professionally distinctive and globally recognised
Python / SAS — Quantitative Analytics mit Großdaten: Use Python and SAS for the statistical analysis, deskriptive and explorative Analyse, and large-scale data preparation that bankweite Kreditrisikomodellierung at Deutsche Bank scale requires — a quantitatively stimulating environment for a Master or PhD-qualified statistician or financial mathematician
Offene Feedbackkultur + Hybrid + Voll- & Teilzeit: Deutsche Bank offers the Role in both Vollzeit and Teilzeit — with hybrid working, flexible Arbeitszeitmodelle, Jobtandem, FitnessCenter Job, pme Familienservice, betriebliche Altersvorsorge, Deutschlandticket, and a culture of diversity and equal opportunity
Position Overview — Risk Methodology Specialist, Deutsche Bank Frankfurt
This Risk Methodology Specialist in the Risk Methodology department (Group Strategic Analytics / Group COO Division) at Deutsche Bank Frankfurt develops, calibrates, and maintains rating methods and credit risk parameters for Deutsche Bank portfolios (focus: DE Retail Germany Portfolio) — conducts simulations of model and parameter change impacts on regulatory capital — communicates with and supports stakeholders in risk assessment — improves internal models and maintains internal policy documents under Basel IV, EBA GL, and SR11-07 standards — supports regulatory model monitoring — participates in internal and external audits — and maintains regular contact with Risk, Business, IT, Finance, and Audit departments — applying Master or PhD-level quantitative expertise in Python/SAS and Kreditrisikomodellierung in one of the world’s leading banking groups.
Why This Role Matters: As Risk Methodology Specialist in Deutsche Bank’s Group Strategic Analytics division in Frankfurt, the rating methods and credit risk parameters you develop and calibrate determine how much regulatory capital Deutsche Bank must hold against its DE Retail Germany portfolio — and therefore directly influence the bank’s ability to deploy capital profitably while meeting the ECB, BaFin, and Basel framework requirements that European systemic banking regulation imposes. When your recalibration of the Probability of Default (PD) model for a German consumer lending sub-segment correctly captures the shift in default behaviour that a macroeconomic stress period has introduced into the historical data and your updated parameter appropriately adjusts the capital requirement for that segment, your regulatory capital impact simulation correctly quantifies the CET1 ratio effect of a proposed methodology change before it is submitted to the regulator for model approval, or your contribution to the EBA GL-compliant internal policy documentation correctly resolves an ambiguity in how the bank’s retail rating methodology maps to the regulatory definition of default that an external audit has flagged — you are not running statistical analyses. You are directly influencing the capital efficiency, regulatory compliance, and credit risk management quality of a bank whose balance sheet runs to hundreds of billions of euros. That is the analytical consequence and genuine financial system significance of excellent Risk Methodology work at Deutsche Bank.
Key Responsibilities — Ihre Aufgaben
Ratingmethoden-Entwicklung & Kreditrisikoparameter-Kalibrierung
- Develop, calibrate, and maintain rating methods and credit risk parameters for Deutsche Bank portfolios — with a primary focus on the DE Retail Germany Portfolio — applying advanced statistical modelling and financial risk methodology expertise to develop the Probability of Default (PD), Loss Given Default (LGD), and Exposure at Default (EAD) models that form the quantitative backbone of Deutsche Bank’s Internal Ratings-Based (IRB) approach to capital allocation
- Perform recalibration of rating methods and credit risk parameters — systematically updating model calibrations as new data accumulates, macroeconomic conditions evolve, and regulatory requirements change, with the statistical rigour and regulatory awareness that ensures recalibrated parameters remain both empirically sound and compliant with EBA GL and Basel IV requirements
- Conduct complex statistical analyses to support decision-making — applying the quantitative skills, exploratory data analysis capability, and large-dataset processing competency in Python and SAS that bank-scale credit risk modelling with millions of retail observations requires, from initial data quality assessment and feature engineering through model development, validation, and documentation
Regulatorisches Kapital, Simulationen & Stakeholder-Kommunikation
- Conduct simulations of the impact of model and parameter changes on regulatory capital — quantifying in advance the CET1 ratio and RWA implications of proposed methodology changes, parameter updates, or model improvements for the DE Retail Germany Portfolio, with the modelling precision and regulatory capital calculation knowledge that credible internal capital impact analysis at Deutsche Bank requires
- Communicate with and support relevant stakeholders in risk assessment and risk analysis — translating complex statistical model developments, parameter changes, and regulatory capital impacts into clear, accurate, and professionally credible communications for Risk, Business, Finance, IT, and senior management audiences with different levels of quantitative technical knowledge
- Maintain regular contact with adjacent departments — Risk, Business, IT, Finance, Audit, and other functions — building the cross-functional professional relationships that allow the Risk Methodology team to understand and incorporate the operational, regulatory, financial reporting, and audit perspectives that inform good credit risk model development and maintenance
Modellverbesserung, Regulatorische Konformität & Audit-Unterstützung
- Improve internal models and maintain internal policy documentation under Basel IV, EBA GL, and SR11-07 standards — applying comprehensive knowledge of the regulatory framework for internal credit risk models to ensure that Deutsche Bank’s retail rating methodology meets the requirements of the current and upcoming regulatory environment, with particular attention to the Basel IV output floor implementation and EBA GL on PD estimation, LGD estimation, and the treatment of defaulted exposures
- Support regulatory model monitoring including maintenance and further development of relevant monitoring components — implementing the ongoing model performance tracking, back-testing, and early warning indicator systems that ensure Deutsche Bank’s credit risk models remain statistically valid, regulatory-compliant, and fit for purpose across changing economic conditions and portfolio composition
- Participate in internal and external audits — providing the model documentation, technical explanations, and analytical support that internal audit, ECB model review teams, and external validation functions require when reviewing Deutsche Bank’s internal credit risk models, with the professional composure and technical depth that audit processes for systemic banking institutions demand
Qualifications & Profile — Ihre Fähigkeiten und Erfahrungen
Essential Requirements
- Master or PhD in a quantitative discipline — (Finanz)Mathematik, Statistik, Ökonometrie, Physik, or comparable — providing the theoretical foundation for complex statistical modelling, model calibration, and regulatory capital calculation in an advanced IRB bank credit risk methodology environment
- Kenntnisse im Bereich Kreditrisikomodellierung — including relevant regulatory requirements, ideally with work experience in credit risk model development and/or experience with internal and external audit reviews in connection with model approvals in the credit risk area
- Sichere Kenntnisse statistischer Software — Python and/or SAS — for data preparation, deskriptive and explorative Analyse, and quantitative modelling of large retail credit datasets
- Strong conceptual and analytical skills — Flexibilität bei der Erarbeitung neuer Themengebiete, and the ability to work proactively, quickly, independently, and solution-orientedly on new tasks
- Verhandlungssicheres Deutsch und Englisch — both spoken and written — for professional stakeholder communication, regulatory documentation, and audit interaction in a bilingual banking environment
- Experience with large projects and communication of complex topics to senior stakeholders — demonstrating the ability to translate quantitative model complexity into executive-level communications
About Deutsche Bank Group Strategic Analytics — Gemeinsam die Zukunft gestalten
Deutsche Bank ist eine der weltweit führenden Banken — mit globaler Präsenz und einem klaren Bekenntnis zu Verantwortung, Qualität, und dem Erfolg seiner Mitarbeitenden. Die Risk Methodology-Abteilung als Teil der Group Strategic Analytics / Group COO Division spielt eine zentrale Rolle bei der Entwicklung bankweiter Risikobewertungsmethoden — Ratingmethoden, Kreditrisikoparameter, regulatorisches Kapital-Management, und Basel IV / EBA GL Compliance — die das Fundament für fundierte Kreditentscheidungen, adäquate Kapitalallokation, und langfristige finanzielle Stabilität legen. Der Risk Methodology Specialist (m/w/d) in Frankfurt ist eingeladen, gemeinsam mit dem Team “jeden Tag das Beste zu geben” — in einer Kultur des offenen Feedbacks, echten Kollegialität, und professionellen Entwicklung, die Deutsche Bank als Arbeitgeber auszeichnet. Bei Fragen zum Rekrutierungsprozess: Nana Darko unter nana.darko@db.com.
Career Excellence: Kreditrisikomodellierung, Basel IV, EBA GL, Ratingmethoden, regulatorisches Kapital, Python, SAS, DE Retail Germany Portfolio — Risk Methodology Specialist, Deutsche Bank Group Strategic Analytics Frankfurt Hesse Germany 2026.
Who Should Apply?
- Quantitative Finance & Credit Risk Specialists — Master/PhD Germany: With Master or PhD in (Finanz)Mathematik, Statistik, or comparable quantitative disciplines and direct Kreditrisikomodellierung experience — seeking a Risk Methodology role at one of the world’s leading banks in Frankfurt, working on Basel IV and EBA GL-compliant internal models for the DE Retail Germany Portfolio
- Basel IV & EBA GL Credit Risk Model Experts — Frankfurt: With specialist knowledge of the Basel IV IRB framework, EBA GL on PD/LGD estimation, and SR11-07 model risk management standards — ready to develop, calibrate, and maintain regulatory-compliant internal credit risk models in Deutsche Bank’s Group Strategic Analytics division
- Python / SAS Quantitative Analysts — Banking & Risk Germany: With strong Python or SAS proficiency applied to large-scale credit portfolio data analysis, statistical model development, and financial risk parameter calibration — seeking a senior quantitative risk role at Deutsche Bank Frankfurt with clear regulatory impact and stakeholder visibility
- Model Risk & Audit-Experienced Risk Professionals — Retail Credit Germany: With experience supporting internal or external model audit reviews, regulatory model submissions, or ECB/BaFin model approval processes — ready to apply that regulatory engagement experience in Deutsche Bank’s Risk Methodology team working on Germany’s largest retail banking portfolio
- Frankfurt Finance Professionals — Deutsche Bank Group COO: Seeking a Risk Methodology Specialist position at Deutsche Bank’s Frankfurt headquarters — in the Group Strategic Analytics / Group COO Division, with Basel IV, Kreditrisikomodellierung, Python/SAS, hybrid working, Voll- & Teilzeit flexibility, Deutschlandticket, betriebliche Altersvorsorge, and Deutsche Bank’s comprehensive employee benefits programme
Recently Opening Job👇
NGS Data Analyst Molecular Oncology Jobs Berlin Germany 2026